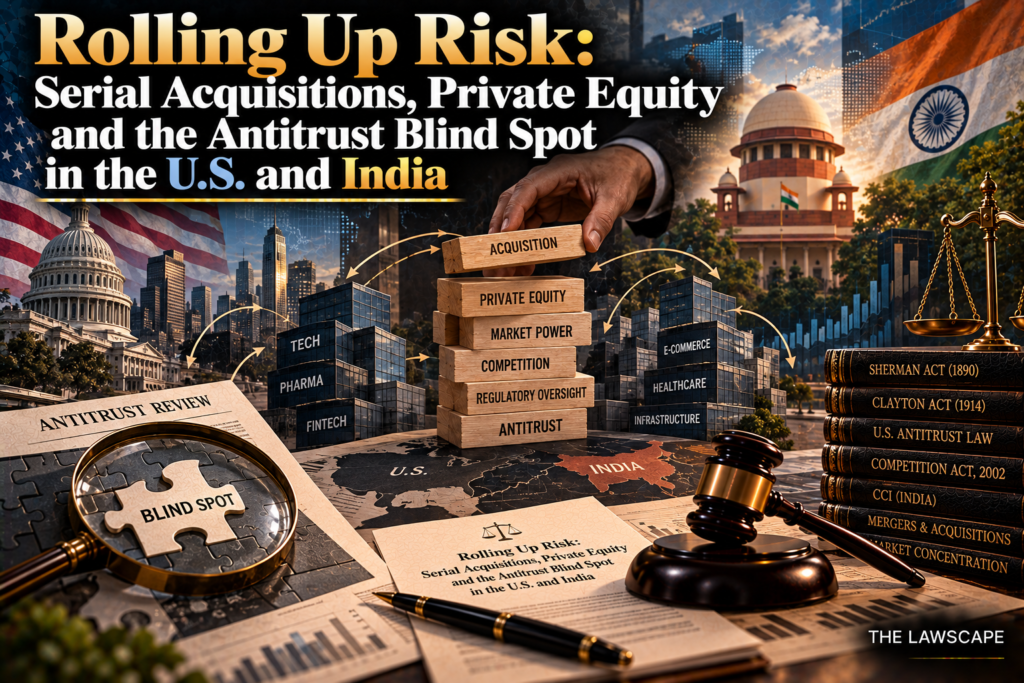
Rolling Up Risk: Serial Acquisitions, Private Equity and the Antitrust Blind Spot in the U.S. and India
Author: Pasi Niveditha
Student, SBRTM Law College affiliated to Yogi Vemana University, Kadapa, Andhrapradesh, India
———————————————————————————————————————————————————————————-
💡 3 Quick Takeaways
- Private equity roll-up strategies can consolidate fragmented markets through a series of individually small acquisitions, potentially escaping merger review when each transaction falls below the applicable notification thresholds.
- The United States’ Hart–Scott–Rodino framework and India’s Competition Act, 2002 address different aspects of merger control, but neither framework’s transaction-specific thresholds necessarily capture the cumulative effects of repeated acquisitions.
- Cumulative acquisition disclosures, appropriately designed aggregation rules and sector-specific monitoring could help competition authorities identify potentially harmful consolidation without subjecting every small transaction to full pre-merger review.
Abstract
Private equity-driven roll-up strategies involve acquiring numerous smaller businesses within the same sector and consolidating them into a larger market platform. This approach exposes a structural challenge in merger control regimes worldwide. Both the United States’ Hart–Scott–Rodino (HSR) framework and India’s Competition Act, 2002 rely on specified thresholds to determine whether transactions must be notified for regulatory review. Although designed to screen significant acquisitions, transaction-specific thresholds may fail to capture the cumulative effects of multiple smaller acquisitions undertaken over time.
This regulatory gap is particularly relevant in fragmented markets such as healthcare, veterinary services and diagnostics, where repeated acquisitions can substantially alter market structure without necessarily triggering pre-merger notification at every stage. This article examines the regulatory frameworks governing serial acquisitions in the United States and India, including the U.S. Federal Trade Commission (FTC) and Department of Justice’s 2024 request for information on serial acquisitions and roll-up strategies, and India’s 2023 introduction of a deal-value threshold. Through a comparative examination of the litigation involving U.S. Anesthesia Partners and Welsh, Carson, Anderson & Stowe, alongside India’s deal-value threshold reform, the article identifies the distinction between reviewing individual transactions and assessing cumulative consolidation. It proposes targeted reforms, including cumulative acquisition disclosures, appropriately calibrated aggregation thresholds and sector-specific monitoring, to improve merger oversight while avoiding disproportionate regulatory burdens on genuinely innocuous transactions.
Keywords: Private equity; serial acquisitions; roll-up strategies; antitrust law; Competition Act, 2002; Hart–Scott–Rodino Act.
1. Introduction
In May 2024, the Federal Trade Commission and the Antitrust Division of the U.S. Department of Justice jointly invited public input on serial acquisitions and roll-up strategies across the economy. The inquiry sought to identify acquisition patterns that could contribute to market consolidation and harm competition.
The underlying concern is that a company may gradually establish substantial control over a market through numerous acquisitions, even where individual transactions fall below the applicable pre-merger notification thresholds. Consequently, a series of small acquisitions may escape the scrutiny that a single transaction producing comparable consolidation would attract.
This concern is not merely theoretical. Private equity firms have pursued acquisition strategies across sectors, including veterinary care, anaesthesiology and diagnostic services. By acquiring independently operated businesses and integrating them into larger platforms, investors can transform fragmented local markets into more consolidated networks.
India faces a related regulatory challenge. Under the Competition Act, 2002, transactions meeting the prescribed criteria for combinations may require notification to the Competition Commission of India (CCI). The Competition (Amendment) Act, 2023 introduced a deal-value threshold, addressing certain transactions that may escape conventional asset- or turnover-based thresholds. However, a threshold designed to capture a single high-value acquisition does not necessarily address the cumulative effects of multiple smaller acquisitions by the same buyer.
This article examines the structural limitations of transaction-specific merger control in both jurisdictions. It argues that effective oversight of roll-up strategies requires greater attention to acquisition histories, repeat-acquirer behaviour and cumulative changes in market structure.
2. Understanding Private Equity and the Roll-Up Strategy
Private equity firms raise pooled capital from investors, including pension funds and other institutional investors, to acquire interests in businesses. Their investment strategies may involve leveraged buyouts, operational restructuring, expansion and eventual exit through resale or a public listing. The underlying commercial objective is generally to increase the value of the investment during the holding period.
The acquisition of HCA Healthcare by a group including Bain Capital and KKR in 2006 illustrates the scale that private equity transactions can reach. HCA subsequently returned to the public markets in 2011. However, a large leveraged buyout should be distinguished from a roll-up strategy, which involves a series of acquisitions within the same or closely related markets.
A roll-up is a specific acquisition strategy in which an investor purchases multiple smaller businesses operating within a particular sector and consolidates them under a common ownership structure or management platform. The acquired businesses may previously have been independently owned, family-run or locally operated.
Where the acquired businesses compete at the same level of the supply chain, the strategy may constitute horizontal consolidation. Traditionally, horizontal mergers have attracted competition-law scrutiny because combining competing businesses can reduce the number of independent market participants and potentially weaken competitive constraints.
A roll-up can produce a similar cumulative effect through multiple transactions spread over several years. Instead of acquiring a large competitor in one transaction, an investor may acquire numerous smaller competitors sequentially. The resulting platform may achieve substantial market presence even though no individual acquisition appears significant when assessed in isolation.
Private equity investment in veterinary care illustrates the relevance of this strategy. The acquisition of independently owned veterinary clinics can gradually bring previously separate providers under common ownership. Depending on the geographic market and the availability of alternatives, this consolidation may affect consumer choice, prices and the competitive conditions facing workers.
The distinction between private equity ownership and anticompetitive conduct is important. Private equity investment does not inherently harm competition, and consolidation may produce operational efficiencies or improve access to services. The regulatory concern arises where the cumulative acquisition strategy substantially weakens competition and existing notification mechanisms fail to identify that risk.
3. The Regulatory Blind Spot: How Thresholds Work
3.1 The United States: Hart–Scott–Rodino Act
The Hart–Scott–Rodino Antitrust Improvements Act of 1976 requires parties to certain mergers and acquisitions to notify the FTC and the Department of Justice before completing a transaction and observe a statutory waiting period. The notification requirement depends on prescribed jurisdictional criteria, including the applicable size-of-transaction threshold and other statutory tests or exemptions.
Transactions that do not trigger the notification requirement may proceed without the HSR pre-merger notification process. However, the absence of a notification obligation does not necessarily mean that a transaction is immune from substantive antitrust scrutiny. U.S. authorities retain powers under applicable antitrust law to challenge acquisitions that violate the law, subject to the relevant legal requirements.
Section 7 of the Clayton Act prohibits acquisitions where their effect may be substantially to lessen competition or tend to create a monopoly. In United States v. Philadelphia National Bank (1963), the Supreme Court discussed the competitive implications of substantial increases in market concentration. Modern merger analysis also considers market structure and concentration, including through the Herfindahl–Hirschman Index (HHI), as addressed in federal merger guidelines.
The difficulty with serial acquisitions is that conventional merger analysis often evaluates a particular transaction against the competitive conditions prevailing at that time. A series of individually small acquisitions may therefore have a cumulative effect that is not fully apparent when each transaction is examined separately.
For example, a private equity sponsor might acquire numerous anaesthesiology practices, veterinary clinics or diagnostic centres over several years. If the acquisitions do not trigger HSR notification, regulators may not receive pre-merger notice of every transaction. By the time the broader pattern becomes apparent, the sponsor may have assembled a substantial platform in a previously fragmented market.
The resulting concern is not that every below-threshold acquisition is unlawful. Rather, transaction-specific notification rules may make it more difficult for authorities to identify and evaluate cumulative consolidation at an early stage.
3.2 India: Competition Act, 2002 and the CCI
India’s Competition Act, 2002 establishes a framework for reviewing combinations that satisfy the applicable statutory conditions and thresholds. Section 5 defines combinations, while Section 6 governs their regulation. Notifiable combinations are assessed by the CCI under the Act, including with reference to whether they cause or are likely to cause an appreciable adverse effect on competition in India.
Historically, asset- and turnover-based thresholds created a potential gap where a target had limited assets or revenue but possessed significant strategic importance, market potential or competitive value. A transaction involving such a target might not trigger notification under the conventional thresholds.
The Competition (Amendment) Act, 2023 introduced a deal-value threshold to address part of this problem. Subject to the statutory conditions and applicable regulations, a transaction exceeding ₹2,000 crore may require notification where the target has substantial business operations in India.
The reform is relevant to acquisitions involving businesses whose competitive significance is not adequately reflected by their assets or turnover. Facebook’s acquisition of WhatsApp in 2014 is frequently discussed in this context because WhatsApp had substantial strategic importance despite its relatively limited revenue at the time.
However, the deal-value threshold addresses a different issue from serial acquisitions. It can bring certain high-value transactions within the notification framework even when conventional financial thresholds are not met. It does not, by itself, ensure that multiple smaller acquisitions by the same sponsor will be assessed cumulatively.
Accordingly, a private equity investor acquiring numerous small diagnostic laboratories or healthcare businesses may present a different regulatory challenge from a single high-value acquisition of a strategically significant technology company.
4. Case Study: U.S. Anesthesia Partners and Welsh, Carson, Anderson & Stowe
In September 2023, the FTC brought proceedings against U.S. Anesthesia Partners, Inc. (USAP) and private equity firm Welsh, Carson, Anderson & Stowe (Welsh Carson). The FTC alleged that the defendants had engaged in a multiyear anticompetitive scheme involving the consolidation of anaesthesiology practices in Texas, with the alleged effect of increasing prices for anaesthesia services.
According to the FTC’s allegations, Welsh Carson established USAP in 2012, after which USAP acquired other anaesthesia practices in Texas. The FTC described the resulting platform as having acquired substantial regional market presence. These assertions formed part of the regulator’s case and should be distinguished from findings ultimately established by a court.
The litigation is relevant to the roll-up debate because it raises questions about the legal responsibility of a private equity sponsor for acquisitions undertaken by a portfolio company and about the availability of remedies against conduct occurring over an extended period.
4.1 The proceedings against Welsh Carson
In May 2024, the district court dismissed Welsh Carson from the FTC’s case. The ruling concerned the requirements for obtaining injunctive relief under Section 13(b) of the FTC Act and the allegations relating to Welsh Carson’s own conduct. The court concluded that the FTC had not adequately established the necessary basis for the requested relief against the sponsor in light of the alleged past conduct and the circumstances described in the complaint.
The ruling should not be interpreted as a general finding that private equity sponsors cannot be liable for anticompetitive conduct associated with portfolio companies. Nor did it establish that roll-up strategies are categorically lawful. Its significance lies in the legal and procedural questions governing the FTC’s claims against the particular sponsor.
The FTC’s claims against USAP proceeded separately. The distinction illustrates the importance of identifying the conduct attributable to a portfolio company and the conduct attributable to its investor when assessing potential liability.
The subsequent settlement involving Welsh Carson in January 2025 further developed the proceedings. The precise terms and legal effect of the settlement, as well as the status of the proceedings against USAP, should be assessed from the relevant court documents and official FTC materials.
4.2 Lessons for merger control
The USAP litigation illustrates the difficulties that may arise when regulators seek to address cumulative consolidation after a platform has already been assembled. The acquisition history, the relationship between the sponsor and the portfolio company, and the legal basis for attributing responsibility all become relevant.
It also highlights the distinction between challenging allegedly anticompetitive conduct after it occurs and reviewing transactions before they are completed. Pre-merger notification can give regulators an opportunity to examine a transaction before market structure changes. Where individual acquisitions do not trigger notification, identifying a broader pattern may require other sources of information and enforcement tools.
The case therefore supports closer examination of repeat-acquirer behaviour. It does not, however, establish that every roll-up is anticompetitive or that a sponsor can avoid liability simply by reducing its ownership interest. Those questions depend on the facts and the applicable legal standards.
5. India’s Deal-Value Threshold: A Comparative Perspective
India’s 2023 deal-value threshold represents a legislative response to the limitations of relying exclusively on the target’s assets and turnover. By taking transaction value into account, the framework can capture certain acquisitions involving targets whose economic or strategic significance is not reflected in conventional financial measures.
The U.S. debate concerning USAP raises a related but distinct concern. It focuses on the cumulative competitive consequences of repeated acquisitions by a platform and the role of the sponsor behind that platform.
The two approaches therefore address different regulatory gaps:
- Deal-value threshold: Helps capture an individual acquisition that meets the prescribed value and substantial-business-operations criteria, even if conventional asset or turnover thresholds are not satisfied.
- Serial-acquisition scrutiny: Seeks to identify the cumulative effect of multiple acquisitions by the same acquirer or affiliated entities over time, including where individual transactions do not independently trigger notification.
The distinction matters because a framework designed to capture a single high-value acquisition may not identify a series of small acquisitions that collectively alter competition in a local or regional market.
India’s deal-value threshold is therefore relevant to the wider debate about merger control, but it should not be treated as a complete solution to the serial-acquisition problem. Whether particular acquisitions require notification depends on the statutory provisions, applicable regulations, transaction structure and relevant thresholds.
6. Why Roll-Up Consolidation Matters: Who Bears the Cost?
The consequences of roll-up strategies should not be framed solely as a concern about independent small businesses being acquired. Competition law is concerned with the competitive process and the effects of market conduct on consumers and other market participants.
6.1 Consumers
Where independent providers in a local market are consolidated into a single platform, consumers may have fewer alternatives. If the resulting business faces weaker competitive constraints, it may gain greater scope to increase prices or reduce service quality.
In the USAP proceedings, the FTC alleged that consolidation in the anaesthesia market had enabled higher prices for patients and other purchasers of healthcare services. These were allegations advanced by the regulator, rather than findings that should be presented without reference to the procedural outcome.
The actual effect of consolidation depends on factors such as market definition, the availability of alternative providers, entry barriers and the extent to which the combined business achieves efficiencies that benefit consumers.
6.2 Workers and monopsony power
Consolidation may also affect labour markets. Where a single platform becomes a dominant employer of professionals within a particular specialty and geographic area, workers may have fewer alternative employers.
This can weaken workers’ bargaining position concerning wages, working conditions and professional autonomy. Competition authorities increasingly consider labour-market effects as part of the broader assessment of competition, although the existence and extent of such effects must be established on the evidence.
6.3 Innovation and service quality
A further concern is the potential effect on innovation and service quality. Competition can encourage providers to improve their services, invest in technology and respond to consumer preferences. Where consolidation reduces competitive pressure, these incentives may weaken.
At the same time, larger platforms may benefit from economies of scale, shared infrastructure and investment capacity. The relevant competition-law question is whether the actual or likely effects of a particular acquisition strategy substantially weaken competition, taking account of the applicable legal framework and supporting evidence.
These considerations apply in both the United States and India. Whether a platform operates in Texas or in an Indian healthcare market, the competitive effects depend on the structure of the relevant market and the conduct of the businesses involved.
7. Suggested Measures
Addressing the potential blind spot in merger control does not require abandoning threshold-based review. Many small acquisitions are unlikely to raise significant competition concerns, and requiring every minor transaction to undergo full pre-merger review could impose disproportionate administrative and commercial costs.
Reform should instead focus on identifying repeat-acquirer patterns and providing regulators with sufficient information to assess cumulative consolidation.
7.1 Cumulative acquisition aggregation
One possible reform is to introduce a carefully calibrated mechanism for aggregating acquisitions by the same acquirer, sponsor or affiliated entities over a defined period.
For example, a rolling look-back period could require regulators to consider the value of acquisitions within the same or related markets over five years. If the aggregate value crossed a prescribed threshold, the acquirer could be required to notify the relevant authority, subject to appropriate jurisdictional criteria and safeguards.
Such a mechanism would need clear rules governing affiliated entities, fund structures, changes in control, market definition and the treatment of transactions that do not raise competitive concerns. Without these safeguards, aggregation could create uncertainty and impose unnecessary burdens on unrelated transactions.
7.2 Disclosure of acquisition history
Another measure is to require parties to disclose relevant prior acquisitions when notifying a transaction. Information about earlier acquisitions in the same or related lines of business can help authorities identify whether an apparently small transaction forms part of a wider consolidation strategy.
The United States has pursued changes to its HSR notification process intended to improve the information available to regulators, including information concerning prior acquisitions. The precise requirements and implementation dates should be checked against the applicable rules and official guidance.
Disclosure does not mean that every acquisition must be challenged. Rather, it can help regulators determine whether a transaction should be assessed in the context of a broader acquisition history.
7.3 Extending the logic of India’s deal-value threshold
India could consider whether its existing framework should be supplemented by rules addressing cumulative acquisitions that may not independently cross the prescribed thresholds.
Any such reform would need to be designed consistently with the Competition Act and its implementing regulations. Relevant factors could include the relationship between the acquiring entities, the markets in which the targets operate, the time period over which acquisitions occur and the extent of cumulative market consolidation.
The objective would be to improve the CCI’s ability to identify potentially significant patterns without assuming that all acquisitions by the same private equity sponsor belong to one anticompetitive strategy.
7.4 Sector-specific monitoring
Competition authorities could also strengthen monitoring in sectors where repeated acquisitions may substantially change local market structure. Healthcare, diagnostics and veterinary services may warrant attention where evidence indicates that consolidation is occurring rapidly or that consumers and workers have limited alternatives.
Monitoring could draw on market-share information, acquisition histories, complaints, price trends and other relevant evidence. Such indicators should serve as prompts for further assessment rather than automatic proof of anticompetitive conduct.
Together, these measures would shift some regulatory attention from individual transactions to acquisition trajectories. Properly designed, they could improve the detection of cumulative consolidation while preserving the efficiency of threshold-based review for transactions that do not raise material competition concerns.
8. Conclusion
Merger control frameworks in the United States and India were developed to assess transactions that meet specified jurisdictional thresholds. While these systems provide a structured mechanism for reviewing significant acquisitions, serial acquisitions can present a different challenge: numerous small transactions may collectively produce substantial changes in market structure without triggering review at every stage.
The U.S. proceedings involving USAP and Welsh Carson illustrate the legal and practical difficulties associated with challenging alleged anticompetitive consolidation after a platform has been assembled. India’s 2023 deal-value threshold addresses a different limitation by bringing certain high-value acquisitions within the merger-control framework even where conventional asset or turnover thresholds are not met.
Neither development, by itself, resolves every concern associated with cumulative roll-up strategies. Potential reforms include improved disclosure of acquisition histories, carefully designed cumulative thresholds and sector-specific monitoring supported by reliable market data.
Ultimately, effective oversight requires a balance between preventing anticompetitive consolidation and preserving legitimate investment and business expansion. The central challenge for regulators in Washington and New Delhi is to ensure that merger control can identify the competitive consequences of acquisition strategies that unfold over time, rather than assessing every transaction in isolation.
Disclaimer: The views expressed in this article are those of the author and do not necessarily reflect the views of The Lawscape.
The Lawscape — clear, practical legal insight for students and future lawyers.